Best Ways to Pay Off Debt Quickly
If you’re looking at your balances and wondering how to pay off debt quickly, the frustrating truth is that most minimum payments are engineered to keep accounts current—not to eliminate balances. On a high-interest account with a sizeable balance, a large share of each minimum payment can go toward interest rather than principal. That’s why paying off debt fast almost always comes down to three levers: paying more, paying less interest, and staying consistent for long enough that the math works in your favor.
Disclosure: This article is general educational information and isn’t personalized financial, tax, or legal advice. Your best options depend on your income, credit profile, and the specific debts you carry.
Below are the strategies that reliably move the needle, roughly ordered from the ones almost everyone should try first to the ones that carry real risk. Let’s take a look at how to pay off debt quickly.
1. Build a Complete Inventory of What You Owe
You can’t attack a target you can’t see. Make a list of every debt and record four things for each:
- Current balance
- Interest rate (APR)
- Minimum payment
- Due date
Include credit cards, personal loans, auto loans, student loans, medical bills, and buy-now-pay-later plans. Many people carry more accounts than they realize, and buy-now-pay-later installment plans are easy to forget because they don’t always appear on a credit report.
Once the list exists, add up the total and the total minimum payments. That combined minimum figure is your baseline—the number you must cover every month no matter which strategy you choose.
2. Stop Letting Minimums Set the Pace
Minimum payments are calculated to satisfy the lender’s requirements, not to free you quickly. When a balance is high relative to the payment, more of that payment goes to interest and less to principal. This is the core reason debt feels like it never moves.
The practical takeaway: your minimums are a floor, not a plan. Any dollar above the minimums on your target debt goes directly to principal, which is what actually shortens your timeline.
3. Pick a Payoff Order: Avalanche or Snowball
There are two mainstream approaches, and both require the same mechanics—pay minimums on everything, then throw every spare dollar at one chosen debt. Either method you choose is a great way to pay off debt quickly.
The avalanche method targets the debt with the highest interest rate first. Mathematically, this saves the most in interest and clears debt fastest for any given total monthly payment. Once the highest-rate debt is gone, you roll that payment onto the next highest rate.
The snowball method targets the smallest balance first, regardless of rate. It costs more in interest than the avalanche in most cases, but it produces quick wins. Those early victories keep people going, and a payoff plan you actually finish beats a mathematically superior plan you abandon.
Honest assessment: if you’re highly motivated by numbers, use the avalanche. If you need momentum, use the snowball. Both work. Quitting doesn’t.
4. Find the “Extra” — From Both Sides of the Ledger
Paying off debt quickly requires a gap between what you earn and what you spend, and you can widen it from either direction.
Cutting expenses is the faster lever. Track your spending for a full month, then categorize it. Look for recurring charges you forgot about, subscriptions you rarely use, insurance you haven’t compared in years, and phone or internet plans that no longer match your usage. Temporary cuts—pausing dining out, delaying upgrades—free up cash without permanently changing your life.
Increasing income has a higher ceiling. Overtime, a part-time job, freelancing, seasonal work, or selling items you no longer use all convert directly into payoff ammunition. A raise or a new job at a higher salary can do more than years of coupon clipping.
Combine both. Cutting alone hits a floor; earning alone can be slow to start. Together they compound.
5. Send Windfalls Straight to Debt
Tax refunds, work bonuses, birthday money, and proceeds from selling unused items are the most commonly wasted payoff opportunities. Because they arrive irregularly, they feel like “extra” rather than part of the plan.
Decide in advance where windfalls go. Better yet, automate the transfer the day the money lands, so it never sits in checking waiting to be spent.
6. Lower the Interest Rate You’re Paying
Reducing your rate is one of the highest-leverage moves available, because every dollar of interest you don’t pay is a dollar that can hit principal instead.
Balance transfer credit cards. Many cards offer a 0% introductory APR on transferred balances for a set period, usually in exchange for a transfer fee calculated as a percentage of the amount moved. This can be genuinely powerful if you can clear the balance before the promotional period ends—because the rate after the promo typically jumps to a normal, much higher APR. Watch the transfer fee, the length of the window, and your credit limit.
Debt consolidation loans. A personal loan can replace several variable-rate payments with one fixed payment and a fixed payoff date. This only helps if the new rate is lower than your current weighted average rate. If your credit isn’t strong, the offered rate may not beat what you already have.
Refinancing individual debts. Auto loan refinancing and student loan refinancing can lower rates. One important caveat: refinancing federal student loans into a private loan means giving up federal protections, which can include income-driven repayment and forgiveness programs. Understand what you’re trading away.
Asking for a lower APR. Calling your card issuer and requesting a rate reduction sometimes works, particularly with a long history of on-time payments. It costs nothing but time, and it occasionally produces results.
Home equity loans and HELOCs. These typically carry lower rates than credit cards—but they convert unsecured debt into debt secured by your home. If you can’t repay, the consequences are far more severe than a bad credit score.
401(k) loans. Borrowing from your retirement account has a certain appeal, but it carries real risk. If you leave or lose your job, the outstanding loan may become due quickly, and unpaid amounts can be treated as distributions subject to income tax and possibly an early-withdrawal penalty. You’re also removing money that would otherwise be growing for retirement.
7. Consider Nonprofit Credit Counseling
Nonprofit credit counseling agencies offer budgeting help and, in some cases, debt management plans. Under a debt management plan, the agency works with your creditors to potentially lower interest rates or fees, and you make a single monthly payment to the agency, which distributes it.
This isn’t a magic fix, and it can affect your credit. If you pursue it, verify the organization’s nonprofit status and check it against consumer protection resources before signing anything.
8. Understand Debt Settlement—and Its Costs
Debt settlement means paying less than you owe. Creditors may agree to accept a reduced amount because a partial payment beats no payment, but this usually happens after you’ve fallen behind, which damages your credit. Forgiven debt may also be treated as taxable income, with certain exceptions.
Many for-profit “debt relief” companies charge fees for settlement services. Consumer protection agencies have repeatedly warned about red flags in this space: fees charged before any debt is settled, promises to erase debt entirely, and instructions to stop paying your creditors. Be extremely cautious, and get independent advice before enrolling in any program.
9. Protect Your Progress
A fast payoff can be undone in a single month of bad decisions. Guard against that:
- Keep every minimum current to avoid late fees and penalty APRs that can spike your rate.
- Automate payments so nothing is missed during a busy month.
- Build a small emergency fund first. Without one, an unexpected car repair or medical bill goes on a credit card and erases your progress.
- Avoid new debt. Consider leaving cards out of your wallet or removing them from saved online checkout.
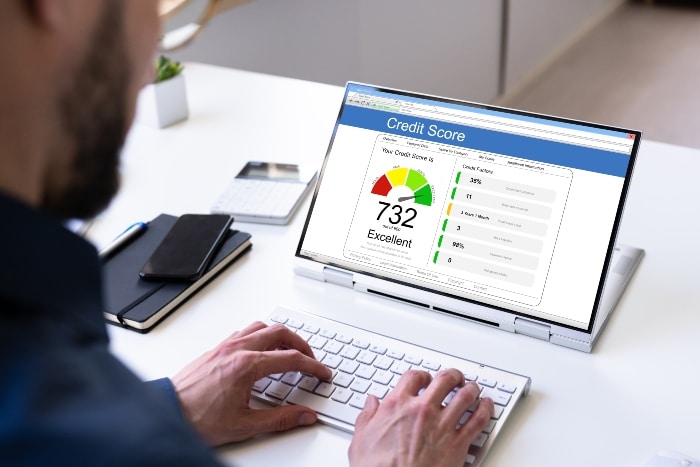
- Check your credit reports for errors, which can drag down your scores and raise the rates you’re offered.
- Be careful about closing old accounts. Closing them can reduce your available credit and affect the length of your credit history.
10. Track the Plan and Adjust Monthly
Payoff plans fail silently. Put your debts in a spreadsheet or an app, note the target payoff date, and update balances monthly. When a balance crosses a milestone, mark it. Visible progress is one of the strongest motivators you have.
11. When Payoff Isn’t Realistic: Bankruptcy
If your debt load is unmanageable relative to your income—or if you’re facing collections, lawsuits, or wage garnishment—bankruptcy may be the honest answer. Chapter 7 generally involves liquidating nonexistent or limited assets to discharge eligible debts, while Chapter 13 sets up a repayment plan. Bankruptcy has serious and long-lasting credit consequences, so it deserves real deliberation with a bankruptcy attorney rather than a snap decision. In the United States, the law requires credit counseling before filing and a debtor education course before discharge.
Watch the Tax Angle
Any debt that’s forgiven, cancelled, or settled for less than you owed may count as taxable income, though exceptions exist—for example, insolvency. Before pursuing settlement or forgiveness, talk to a tax professional about what you might owe.
Putting It All Together
A workable fast-payoff plan looks like this:
- List every debt with its balance, rate, minimum, and due date.
- Choose avalanche or snowball based on what will keep you going.
- Calculate how much extra you can throw at debt each month through cuts and added income.
- Lower your rates where it makes sense—balance transfers, consolidation, refinancing, or a simple phone call.
- Automate minimums and the extra payment.
- Route every windfall to the target debt.
- Review and adjust monthly.
Paying off debt quickly rarely comes from one clever move. It comes from stacking small advantages—a lower rate here, a cancelled subscription there, an extra payment everywhere—and repeating them for months until the balances stop being a source of stress and start being a line item you’re closing out one by one. Start using these methods to pay off debt quickly.
3 Comments